Cross Border Planning, International Investments and Estate Tax Advisory
For families whose assets, heirs and tax residency no longer sit in one country. India taxes nothing on inheritance. The countries your family lives in often do, and the exposure is frequently discovered too late to plan around.
01 Four situations, one underlying problem
Cross border wealth does not fail because the investments are wrong. It fails because two or more tax systems each apply their own logic to the same asset, and nobody holds the whole picture.
|
A The Returning Indian You have worked abroad for years and are moving back. You have a 401(k) or an ISA, employer stock, a house you may keep, and a short statutory window in which your foreign income is still outside the Indian net. What you do in that window is largely irreversible afterwards. |
B The Departing Resident You are leaving India for work, study or a transfer. Your resident accounts, demat holdings, insurance and PPF all need repositioning under FEMA, and the country you are moving to may tax you on assets you have held in India for decades. |
|
C The Globally Split Family You are resident in India. Your children are citizens or long term residents of the United States, the United Kingdom, Canada or Australia. The estate you intend to leave them will be taxed, or will trigger a deemed disposal, in a jurisdiction you do not live in. |
D The Non Resident Investor You live in the Gulf, Singapore or the UK and want disciplined exposure to India, or you are an Indian resident who wants genuine global diversification. Both need to be built around the compliance and reporting regime you actually live under, not the one that is convenient. |
The asymmetry most families miss
India abolished estate duty in 1985 and has levied no inheritance tax since. It is easy to conclude that succession is a documentation exercise rather than a tax one. For a family that is entirely Indian, that is broadly true.
It stops being true the moment a US listed share, a UK property, a US citizen child or a long term UK resident spouse enters the picture. The tax then does not attach to where you live. It attaches to where the asset is, or to where the person receiving it is.
THE SINGLE MOST COMMON EXPOSURE WE SEE
An Indian resident holds US listed shares or a US domiciled ETF, often through an offshore broker in Dubai or Singapore, in the belief that holding outside America keeps it outside the American tax net. It does not. Shares of a US corporation are US situs property for federal estate tax wherever the account sits. A US domiciliary is currently sheltered to USD 15,000,000. A non residentnon citizen is sheltered to USD 60,000, a figure unchanged since 1988, with the excess taxed at rates rising to 40 percent. India has no estate tax treaty with the United States, so there is no treaty relief to fall back on.
|
USD 60,000 US estate tax exemption available to a non residentnon citizen on US situs assets. Not indexed to inflation. |
250 : 1 Ratio between the US domiciliary exclusion and the non resident exemption for 2026. |
3 years Maximum length of the Indian RNOR window, and often only two. It is the planning window on return. |
02 Cross border financial planning
Residency is the master variable. Almost every other decision, on where to hold an asset, when to sell it and who should own it, follows from what your residency status will be and when it changes.
Residency transition and the RNOR window
An individual returning to India is ordinarily a Resident but Not Ordinarily Resident before becoming a full resident. During that period, foreign income and gains on foreign assets sit outside the Indian tax net. Once ordinary residence begins, worldwide income becomes taxable in India and every foreign asset must be disclosed in Schedule FA of the return, whether or not it produced any income.
The window is short and its length depends entirely on the date of return within the financial year and the prior absence history. We model it for the specific facts rather than assuming it, then work out what should be crystallised, restructured, consolidated or closed while it is open.
|
WORK STREAM |
WHAT IT COVERS |
|
Residency modelling |
Day count projections across jurisdictions, RNOR eligibility and duration, the timing of the return or departure itself where it is still moveable, and treaty tie breaker analysis where two countries both claim you. |
|
Pre arrival restructuring |
Decisions taken before ordinary residence begins: which foreign holdings to sell into the window, which to retain, whether foreign retirement accounts should be drawn or left, and how existing offshore structures will be characterised once you are back. |
|
FEMA repositioning |
Conversion of resident accounts to NRO and NRE on departure, or the reverse on return, redesignation of demat and mutual fund folios, treatment of PPF and small savings, and the position on property held on either side. |
|
Repatriation sequencing |
Moving money in the right order and through the right channel. The USD 1 million per financial year repatriation route for NRO balances, LRS for residents, and the documentation trail that has to exist before, not after, the remittance. |
|
Disclosure architecture |
Schedule FA, Form 67 foreign tax credit, and the reporting that runs the other way: FBAR and Form 8938 for US persons, and the equivalent regimes elsewhere. Built once, maintained annually. |
|
Cash flow and goal planning |
The ordinary work of financial planning, done in two or more currencies: education abroad, a retirement that may straddle countries, and the currency in which each liability will actually fall due. |
WHY THE DISCLOSURE WORK IS NOT ADMINISTRATIVE
Failure to disclose a foreign asset in Schedule FA carries a penalty of INR 10 lakh per year of default under the Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015, separate from any tax on the income. A de minimis relief applies where the aggregate value of the assets, other than immovable property, does not exceed INR 20 lakh, widened from a much narrower relief with effect from 1 October 2024. A dormant foreign brokerage account with a small balance and no income is still a reportable asset.
Remittance and the Liberalised Remittance Scheme
A resident individual may remit up to USD 250,000 per financial year under the LRS for permitted current and capital account transactions combined. Since 1 April 2025 tax is collected at source above an annual threshold of INR 10 lakh, at 20 percent for investment and most other purposes and 5 percent for education and medical remittances, with education funded by a qualifying education loan exempt. TCS is creditable against your final tax liability and is not a cost, but it is a cash flow event that planning should anticipate rather than discover.
03 International investments
The investment question and the compliance question cannot be answered separately. The right fund for a resident Indian is frequently the wrong fund for the same family once a US person is among the beneficiaries.
The routes available, and what each is good for
|
ROUTE |
WHAT IT GIVES ACCESS TO |
PRINCIPAL CONSIDERATIONS |
|
Direct LRS |
Foreign brokerage account, global equities, ETFs and bonds held in your own name offshore. |
Counts against the USD 250,000 annual limit. TCS applies above the threshold. Raises situs and probate questions in the country where the account and the securities sit. |
|
GIFT City IFSC |
Foreign currency bank accounts, global and Indian securities via the IFSC exchanges, IFSC domiciled funds and AIFs, portfolio management, family investment funds, and USD denominated insurance and annuity products. |
RBI widened LRS access to IFSCs in July 2024, so the full annual allowance can now be routed through a single Indian regulated gateway. Note that the section 80LA tax holiday belongs to the IFSC unit, not to you as an investor. |
|
Domestic feeder funds |
Indian mutual fund schemes investing in overseas securities. |
No LRS usage and no offshore account to report. Subject to the industry level overseas investment limits, which have periodically been closed to fresh inflows. |
|
Non US domiciled ETFs |
Broad global and US market exposure through funds domiciled outside the United States, typically Irish UCITS. |
The standard structural answer to US situs estate tax exposure for a non US person. Withholding tax treatment on underlying dividends differs from a US domiciled equivalent and should be compared on a net basis. |
Two traps that decide the structure
|
PFIC, for US persons holding Indian funds An Indian mutual fund scheme is a passive foreign investment company in US eyes. Absent an election that Indian asset managers are generally not equipped to support, gains and excess distributions are taxed under the default regime at the highest ordinary rate for each year of the holding period, with an interest charge on the deferred tax, and reported per fund per year on Form 8621. A US citizen or green card holder in your family therefore changes what should be bought in India, not merely how it is reported. Direct equities, and structures outside the fund wrapper, behave very differently. |
US situs, for everyone who is not a US person Shares of US corporations, US real estate and tangible property physically in America are US situs assets for estate tax regardless of where the account is held. US bank deposits not connected with a US business, and qualifying portfolio interest debt, are not. The consequence is that where a global equity allocation is held matters as much as the allocation itself. A family can hold the same underlying exposure with a very different death tax profile depending on the domicile of the fund used to hold it. |
What we do on the investment side
• Asset allocation across currencies and jurisdictions, sized to goals that may fall due in different currencies at different times.
• Selection of the holding route and fund domicile with the family's tax profile as a binding constraint, not an afterthought.
• Consolidation of legacy holdings accumulated across several countries into a structure that can actually be reported and eventually transferred.
• Review and monitoring against the reporting calendar of every jurisdiction the family touches.
04 Estate and succession tax advisory
There is no single answer to what happens to your estate, because there is no single jurisdiction that decides it. The work is to map, for each material asset, which country will assert a claim and on what basis, and then to reduce the number of surprises.
How the corridors differ
|
JURISDICTION |
THE CHARGE ON DEATH |
WHAT IT MEANS FOR AN INDIAN CONNECTED FAMILY |
|
India |
None. Estate duty abolished for deaths on or after 16 March 1985. No inheritance tax and no tax on the heir. |
Succession here is a documentation and control question, not a tax one. That makes it easy to assume the same holds abroad. It does not. |
|
United States |
Federal estate tax at rates to 40 percent. USD 15,000,000 exclusion for a US citizen or domiciliary in 2026. USD 60,000 for a non residentnon citizen on US situs assets. |
No estate tax treaty exists between India and the United States, so no treaty relief is available. The exposure is triggered by the situs of the asset, not by where you live. Gifts to a non citizen spouse are also capped, at USD 194,000 for 2026, rather than unlimited. |
|
United Kingdom |
Inheritance tax at 40 percent, or 36 percent where at least a tenth of the net estate goes to charity. Nil rate band GBP 325,000 and residence nil rate band GBP 175,000, both frozen to 5 April 2031. |
Domicile ceased to be the connecting factor on 6 April 2025. Worldwide IHT now follows long term residence, being UK tax resident for at least ten of the previous twenty years, with a tail of three to ten years after leaving. This is a material change for Indian families with a member who has been in the UK a long time. |
|
UAE and GCC |
No personal income tax, no estate tax and no inheritance tax. |
The risk is succession law rather than tax. Federal Decree Law 41 of 2022 gives non Muslims testamentary freedom over UAE assets and sets a gender equal default split. A registered will, through the DIFC Wills Service or ADGM, remains essential, both to override the default and to stop heirs applying a foreign law you did not choose. |
|
Singapore |
None. Estate duty abolished for deaths on or after 15 February 2008. |
Clean on the tax side. The planning work is situs, probate and the treatment of assets held there by someone tax resident elsewhere. |
|
Australia |
No inheritance tax. The charge comes through capital gains instead. |
Two distinct events. Ceasing Australian residency triggers a deemed disposal of most assets at market value unless an election is made. Separately, where an asset passes from a deceased Australian to a foreign resident beneficiary, the usual rollover is lost and the gain crystallises in the deceased's final return. An Indian resident child inheriting an Australian parent's portfolio can therefore trigger Australian tax in the parent's estate. |
|
Canada |
No estate tax. A deemed disposition of capital property at fair market value immediately before death, taxed in the terminal return. |
A spousal rollover can defer the gain where property vests in a surviving spouse within thirty six months. Leaving Canada triggers its own departure tax with defined exclusions and elections, which is often the more immediate issue for a family moving back to India. |
|
New Zealand |
None. Estate duty abolished for deaths on or after 17 December 1992, gift duty from 2011. |
The live issue during residence is the foreign investment fund regime, which taxes New Zealand residents on deemed income from offshore holdings including Indian mutual funds and listed equities, whether or not anything is distributed or sold. The rules are being reformed and should be checked at the time. |
Positions confirmed against primary sources as at 22 August 2026. Thresholds, rates and residence tests change, sometimes with retrospective or transitional effect. No figure in this table should be relied upon without confirmation at the time of the decision.
What the estate advisory engagement produces
1 Asset and connection map
Every material asset listed with its situs, its legal owner, its title basis, and the residency, domicile and citizenship of every person who might receive it. Most families have never had this on one page, and the gaps in it are usually where the exposure sits.
2 Exposure quantification
For each jurisdiction that has a claim, an estimate of what would be payable if the event happened today, what relief or credit is available, and where the liquidity to pay it would come from. Death taxes fall due before assets can usually be sold, which is a cash flow problem as much as a tax one.
3 Options and trade offs
Where structural change is available, we set out what it does, what it costs and what it gives up in control. Where nothing sensible can be done, we say so. Some exposures are better funded for than restructured away.
4 Instruction set for your professional advisers
A brief your lawyer, chartered accountant or overseas CPA can act on, so that the will, the trust deed and the tax filings in each country are drafted against one coherent plan rather than three partial ones.
5 Review discipline
Residency changes, statutes change, and children acquire citizenships. The plan is revisited on a defined cycle and on any triggering event, because a cross border plan that is not maintained becomes wrong quietly.
05 What we do, and what we co-ordinate
We are a SEBI Registered Investment Adviser. We are not a law firm, not a chartered accountancy practice, and not licensed to practise tax in a foreign jurisdiction. We think the honest version of that boundary is more useful to you than a claim to do everything, so it is set out plainly below. You deal with one team that holds the plan, and we bring in the specialist where a specialist is required.
|
Dilzer advises on directly • Cross border asset allocation, product and route selection • Residency transition modelling and RNOR window planning • Repatriation and remittance sequencing under FEMA and LRS • Exposure mapping and quantification across jurisdictions • Goal, retirement and education planning in multiple currencies • Risk management and the funding of an identified estate tax liability • Consolidation, review and ongoing monitoring of the whole picture • Co-ordination of the family's advisers around a single plan |
We co-ordinate, and do not ourselves provide • Preparation and filing of foreign tax returns, through partner CPAs and CAs • Drafting of wills, codicils and probate applications, through partner counsel • Trust formation, trusteeship and trust administration • Formal legal opinions on foreign tax or succession law • Registration of DIFC or ADGM wills, through the relevant registry and counsel • Company formation and corporate structuring abroad • Foreign exchange dealing and remittance execution |
On the India and United Kingdom estate duty convention of 1956
An instrument from the estate duty era remains in force between India and the United Kingdom and has historically been argued to shelter an India domiciled individual from UK tax on non UK assets. Its interaction with the residence based regime introduced on 6 April 2025 is unresolved and no definitive guidance has been published. We will raise it where it is relevant, and we will refer it to UK counsel. We will not present it to you as settled protection, because it is not.
06 How we work
We are fee only. We do not earn commission, brokerage or any consideration from a product manufacturer, so the advice you receive carries no embedded incentive to recommend one instrument over another.
1 Discovery call, 30 minutes, no fee
Thirty minutes, at no cost and with no obligation, to establish the facts that determine everything else: current and expected residency of each family member, citizenship, where the assets sit, and what is already in place. We tell you at the end whether we think we can add anything, and roughly what it would involve.
2 Scope and engagement letter
A written scope, fee and timeline before any work starts, together with the risk profiling and suitability assessment that SEBI requires of a registered adviser before advice is given.
3 Analysis and draft plan
Document gathering, modelling, and where necessary a question put to a partner specialist in the relevant jurisdiction. You see a draft and we work through it together before anything is finalised.
4 Implementation support
Account opening, redesignation, documentation and sequencing, executed in the right order with the paperwork created at the time rather than reconstructed later.
5 Ongoing review
Periodic review against the reporting calendar of every jurisdiction that applies, and an immediate review on any change in residency, citizenship, family structure or law.
|
Fee basis Fee only, agreed in writing in advance, and charged within the limits prescribed under the SEBI (Investment Advisers) Regulations, 2013. No commission from any product provider. |
Confidentiality Everything you share is treated as confidential client information. Where we bring in a partner specialist we tell you first and share only what that engagement requires. |
Working across time zones We have advised families in the UK, the US, the UAE, Singapore, Australia, New Zealand and Brazil for two decades. Meetings are scheduled to your time zone, not ours. |
To begin: a complimentary 30 minute discovery call
Write to business@dilzer.net and dilzerconsultants@gmail.com, or request a call through dilzer.net, with a one paragraph description of your situation and the jurisdictions involved. The first 30 minute call is free and carries no obligation. If your matter is time sensitive, for example a return to India already scheduled or a transaction in progress, please say so, because the sequence of events frequently matters more than the analysis.
07 Disclosures
Nature of this document
This document is issued by Dilzer Consultants Private Limited, a SEBI Registered Investment Adviser, registration number INA200002239, for information and education. It describes services offered. It contains no investment recommendation, no product recommendation, no tax opinion and no legal opinion, and nothing in it should be read as a solicitation to transact in any security or product.
Not personalised advice
This document has been prepared without reference to the financial circumstances, tax residency, citizenship, investment objectives, risk tolerance, risk capacity or particular needs of any person. Advice under the SEBI (Investment Advisers) Regulations, 2013 is provided only after a documented risk profiling and suitability assessment and within an agreed advisory relationship governed by a written engagement.
Tax, legal and regulatory content
References to tax law, succession law, exchange control and reporting obligations in India, the United States, the United Kingdom, the United Arab Emirates, Singapore, Australia, Canada and New Zealand are general summaries confirmed against publicly available primary sources as at 22 August 2026. They are not exhaustive, they simplify materially, and they will change. Several of the positions described are subject to scheduled change or to reform proposals that were not enacted as at that date. Dilzer Consultants Private Limited is not a law firm, is not a chartered accountancy practice and is not authorised to practise tax or law in any foreign jurisdiction. No reader should act, or refrain from acting, on the basis of anything in this document without obtaining advice from a qualified professional in the relevant jurisdiction addressed to their own facts.
Investment risk
Investments in securities are subject to market risk, including the possible loss of the principal amount invested. Investments denominated in a foreign currency carry exchange rate risk in addition to market risk, and a favourable investment return can be reduced or reversed by currency movement. Past performance is not indicative of future results. No return is assured or guaranteed, and no outcome described in this document is promised.
Third party information
Certain information has been obtained from public sources believed to be reliable. While reasonable care has been taken, Dilzer Consultants Private Limited does not warrant the accuracy, completeness or timeliness of third party information and accepts no liability for any loss arising from its use.
Conflicts and compensation
Dilzer Consultants Private Limited operates on a fee only basis and does not receive commission, brokerage, referral fee or any other consideration from any product manufacturer or distributor in respect of advice given to clients. Any material conflict of interest will be disclosed. Dilzer Consultants Private Limited, its personnel and its associates may hold positions in securities discussed with clients, and any such holding will be disclosed on request.
Use of artificial intelligence
This document was prepared with the assistance of an artificial intelligence research system used to retrieve and verify publicly available source material. AI generated analysis can contain errors. The content has been prepared under human supervision and responsibility for it rests with Dilzer Consultants Private Limited.
Grievance redressal
Any grievance may be addressed in the first instance to the Principal Officer, Dilzer Consultants Private Limited, 404 Embassy Centre, 11 Crescent Road, Bangalore 560001. If the complaint is not resolved to your satisfaction, you may escalate it to SEBI through the SCORES portal at scores.sebi.gov.in, or seek resolution through the Online Dispute Resolution portal at smartodr.in.
Registration disclaimer
Registration granted by SEBI, membership of a SEBI recognised supervisory body and certification from the National Institute of Securities Markets in no way guarantee the performance of the intermediary or provide any assurance of returns to investors.
|
Dilzer Consultants Private Limited 404 Embassy Centre, 11 Crescent Road Bangalore 560001, Karnataka, India business@dilzer.net dilzerconsultants@gmail.com dilzer.net |
Registrations SEBI Registered Investment Adviser INA200002239 CIN U74140KA1984PTC006171 BSE Enlistment 1338 |
Definition of NRI.
1) Who is a NRI?
An NRI (Non-Resident Indian) is an individual of Indian nationality or origin who resides outside India for employment, business, or other purposes that indicate their intention to stay outside India for an uncertain period. The definition and tax implications for NRIs are governed by the Income Tax Act of India.
2) Who is considered to be a NRI?
Under the Income Tax Act, the residential status of an individual is determined based on their physical presence in India during a financial year (April 1 to March 31). An individual is considered an NRI if they meet the following criteria:
Non-Resident:
- Has been in India for less than 182 days during the financial year, or
- Has been in India for less than 60 days during the financial year and less than 365 days during the preceding four years.
NRI Taxable Income & Taxation
1) What are the incomes which is Taxable and Not Taxable in India for NRIs?
a) Income Taxable in India 500:
- Income Received in India: Any income received or deemed to be received in India is taxable.
- Income Accrued in India: Any income that accrues or arises or is deemed to accrue or arise in India is taxable.
b) Income Not Taxable in India:
- Foreign Income: Any income earned and received outside India is not taxable for NRIs.
2) What are different types of Income & their Tax implications for NRIs?
- Salary Income: Taxable if received in India or for services rendered in India.
- Rental Income: Taxable in India if the property is situated in India. Standard deductions and exemptions apply as for resident taxpayers.
- Interest Income:
o NRE Account: Interest earned on a Non-Resident External (NRE) account is tax-free.
o FCNR Account: Interest earned on Foreign Currency Non-Resident (FCNR) accounts is tax-free.
o NRO Account: Interest earned on a Non-Resident Ordinary (NRO) account is fully taxable.
- Capital Gains:
o Sale of Assets in India: Gains from the sale of assets such as property, shares, and securities in India are taxable.
o Short-Term Capital Gains: Taxable at applicable rates based on the type of asset.
o Long-Term Capital Gains: Taxable at 20% with indexation benefit for property and other assets, and at 10% without indexation for equity and equity mutual funds.
- Dividends: Dividends received from Indian companies are taxable in the hands of the NRI at the applicable slab rates. The company paying the dividend withholds tax at source.
- Special Provisions for Investment Income: Income from investments made in India in certain specified assets is taxed at 20%, and long-term capital gains on these assets are taxed at 10%.
3) What is DTAA?
India has entered into DTAA with various countries to avoid double taxation of income. NRIs can benefit from these treaties to reduce their tax liability in India and their country of residence. Provisions include:
- Tax Credit: Credit for taxes paid in one country against the tax liability in another.
- Exemptions and Lower Rates: Income may be exempt or taxed at a lower rate under the DTAA.
NRI Mutual Fund Related FAQs
1) Can NRIs invest in Mutual Funds (MFs)? Do they require any special permission from the RBI?
NRIs can invest in the Mutual Funds on repartiable as well as non – repartiable basis. They don’t require any special permission in this regard from RBI. RBI has vide Notification No. FEMA 20/2000 dated May 3, 2000 granted general permission to NRIs to purchase, on a repatriation as well as non repatriation basis the units of domestic mutual fund.
2) Are there any specific procedures to be followed for making the investment on a repartiable/non repartiable basis?
Investment on a repartiable basis
An NRI can invest in the domestic mutual funds on repartiable basis, provided the consideration is paid either by inward remittance through normal banking channels viz., Rupee drafts purchased abroad or out of funds held in his NRE/FCNR account.
In case of Indian Rupee drafts purchased aboard or if investment is made from funds in NRE/FCNR A/c a debit certificate from the issuing bank shall be required.
Investment on a Non - repartiable basis
An NRI can invest in the domestic mutual funds on Non- repartiable basis, provided the consideration is paid either by inward remittance through normal banking channels or out of funds held in his NRO/NRSR/NRNR account.
3) What is various Taxes for NRIs while investing into Mutual Funds?
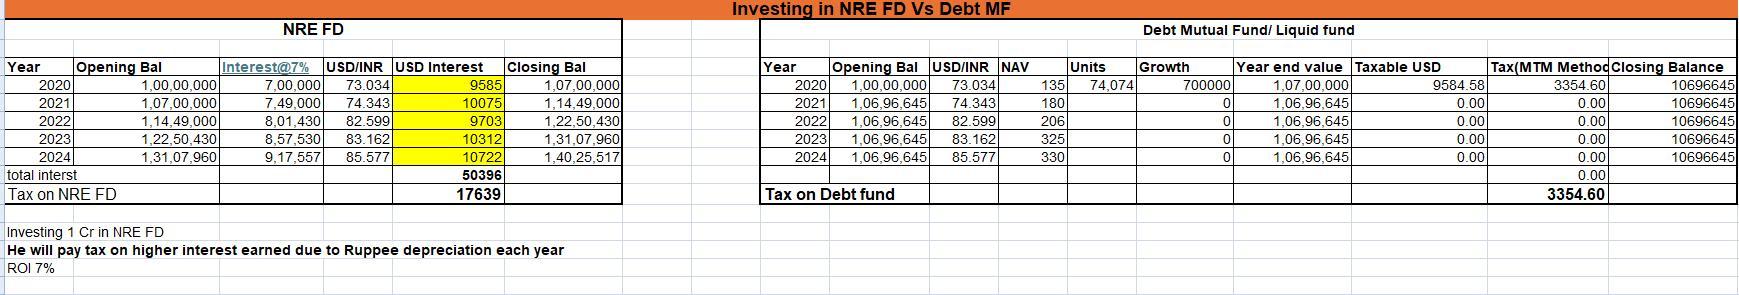
Investing in mutual funds as an NRI (Non-Resident Indian) involves specific tax implications in India. The tax treatment depends on the type of mutual fund (equity or debt) and the holding period. The tax implications for NRIs investing in mutual funds in India are as follows:
Types of Mutual Funds
- Equity Mutual Funds: Funds that invest at least 65% of their corpus in equity and equity-related instruments.
- Debt Mutual Funds: Funds that invest primarily in fixed-income securities like bonds, government securities, and money market instruments.
- Hybrid Funds: Funds that invest in a mix of equity and debt instruments.
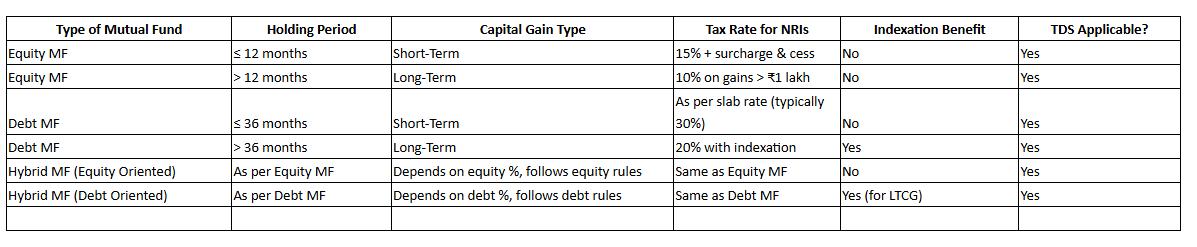
Investment options for NRIs
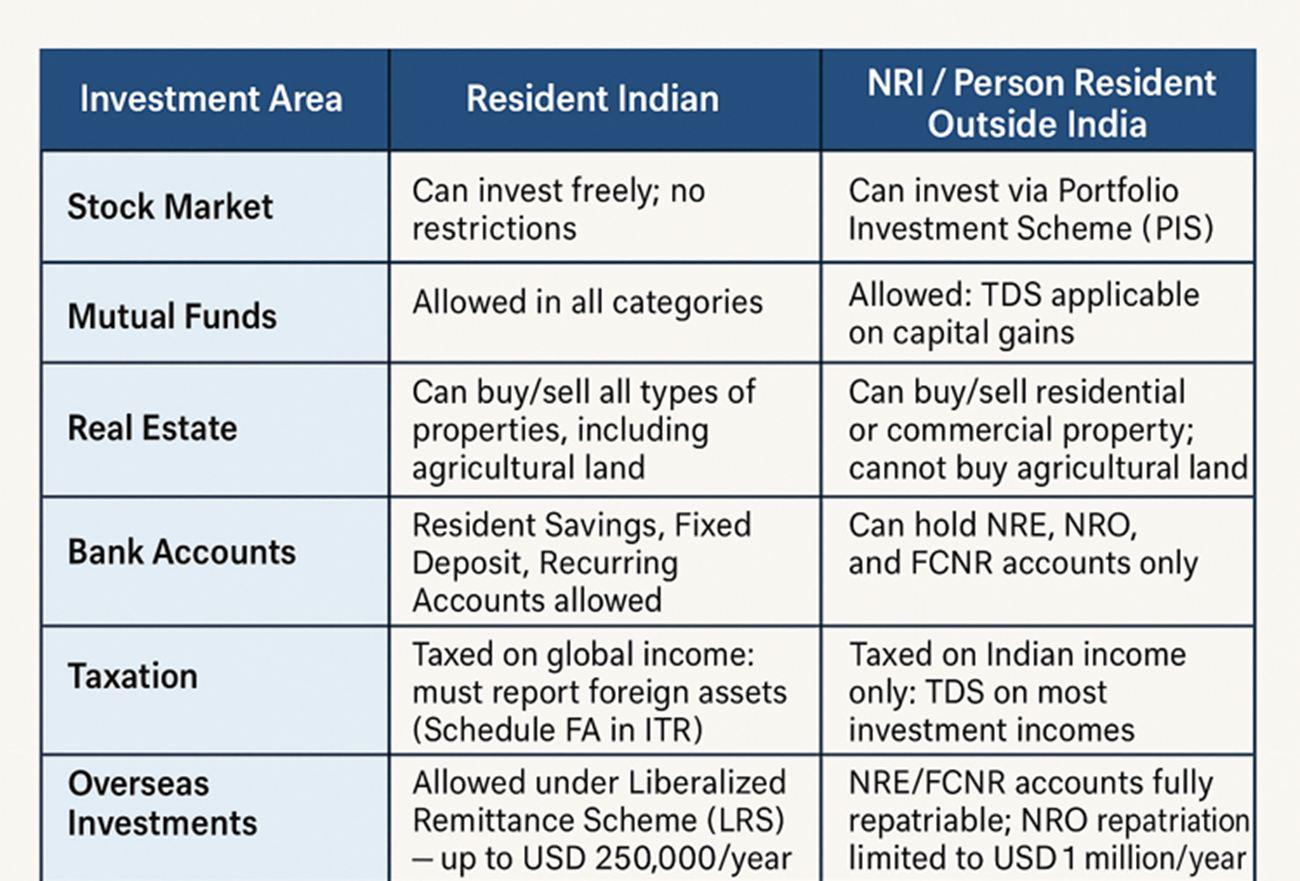
How are debt MFs better than NRE FDs for US NRIs
4) How can NRIs Repatriate their Mutual Funds from India?
NRIs can repatriate the redemption proceeds of mutual fund investments, subject to specific conditions:
- Investments from NRE/FCNR Accounts: Both principal and gains are fully repatriable.
- Investments from NRO Account: Only the capital gains (not the principal) are repatriable, subject to applicable limits and conditions set by the Reserve Bank of India (RBI).
Bank Account Types, Regulations & Requirements
1) What are various types of bank accounts offered for NRIs?
NRIs (Non-Resident Indians) have various options for maintaining bank accounts in India, each tailored to different needs, such as savings, investment, repatriation, and everyday transactions. Here are the primary types of bank accounts available for NRIs:
1. NRE (Non-Resident External) Account
Purpose: To park overseas earnings in India in Indian Rupees.
Features:
- Currency: Maintained in Indian Rupees (INR).
- Repatriability: Both principal and interest are fully repatriable to the NRI's country of residence without restrictions.
- Taxation: Interest earned is tax-free in India.
- Deposits: Can be made from foreign income or by transferring from another NRE/FCNR account.
- Withdrawals: Can be made freely in INR for local expenses.
- Types of Accounts: Savings, current, recurring deposit, and fixed deposit accounts.
2. NRO (Non-Resident Ordinary) Account
Purpose: To manage income earned in India, such as rent, dividends, pension, etc.
Features:
- Currency: Maintained in Indian Rupees (INR).
- Repatriability: Principal amount is not repatriable beyond a set limit (currently up to USD 1 million per financial year), while interest is fully repatriable.
- Taxation: Interest earned is subject to TDS (Tax Deducted at Source) as per applicable slab rates.
- Deposits: Can be made from income earned in India or by transferring from another NRO account.
- Withdrawals: Can be made freely in INR for local expenses.
- Types of Accounts: Savings, current, recurring deposit, and fixed deposit accounts.
3. FCNR (Foreign Currency Non-Resident) Account
Purpose: To maintain overseas earnings in foreign currency without converting to INR.
Features:
- Currency: Maintained in foreign currencies such as USD, GBP, EUR, JPY, AUD, CAD, etc.
- Repatriability: Both principal and interest are fully repatriable.
- Taxation: Interest earned is tax-free in India.
- Deposits: Can be made from overseas income or by transferring from another FCNR/NRE account.
- Withdrawals: Can be made in foreign currency.
- Types of Accounts: Fixed deposit accounts only (terms range 1-2 years).
2) What are the documents required to Open various NRI Bank accounts?
To open an NRE, NRO, or FCNR account, NRIs typically need to provide the following documents:
- Proof of NRI Status: Passport, visa, and/or residence permit.
- Proof of Overseas Address: Utility bills, rental agreement, or overseas bank statement.
- Proof of Identity and Address in India: Aadhar card, PAN card, or similar documents.
- Photographs: Recent passport-sized photographs.
3) What are the various Rules & Limits for Repatriation for NRIs?
NRIs (Non-Resident Indians) often need to transfer money between India and their country of residence. The rules and regulations governing the repatriation of funds from India are designed to facilitate these transfers while ensuring compliance with Indian laws.
Types of Accounts and Repatriation Rules
1. NRE (Non-Resident External) Account
Purpose: To park overseas earnings in India.
Repatriability:
- Both the principal and interest amounts are fully and freely repatriable.
- Funds in this account can be transferred to a foreign account without any restrictions.
Conditions:
- Deposits can be made from foreign earnings or by transferring from another NRE/FCNR account.
- There are no limits on the amount that can be repatriated.
2. NRO (Non-Resident Ordinary) Account
Purpose: To manage income earned in India, such as rent, dividends, pension, etc.
Repatriability:
- Interest earned is fully repatriable after paying applicable taxes.
- Principal repatriation is allowed up to USD 1 million per financial year (April to March), including all other eligible assets.
Conditions:
- The account holder must submit appropriate documents, including Form 15CA and Form 15CB (signed by a Chartered Accountant) to certify that taxes have been paid.
- Prior approval from the Reserve Bank of India (RBI) is not required within the repatriation limit.
3. FCNR (Foreign Currency Non-Resident) Account
Purpose: To maintain overseas earnings in foreign currency without converting to INR.
Repatriability:
- Both the principal and interest amounts are fully and freely repatriable.
- Funds can be transferred to a foreign account in the currency of the deposit.
Conditions:
- Deposits can be made from foreign earnings or by transferring from another FCNR/NRE account.
- There are no limits on the amount that can be repatriated.
4) What are the documents required for Repatriation?
Below are some of the key documents required for Repatriation:
- Form 15CA: A declaration of remittance submitted by the remitter.
- Form 15CB: A certificate from a Chartered Accountant confirming that applicable taxes have been paid or that the transaction is not taxable.
- Bank Forms: Specific forms provided by the bank for processing the repatriation request.
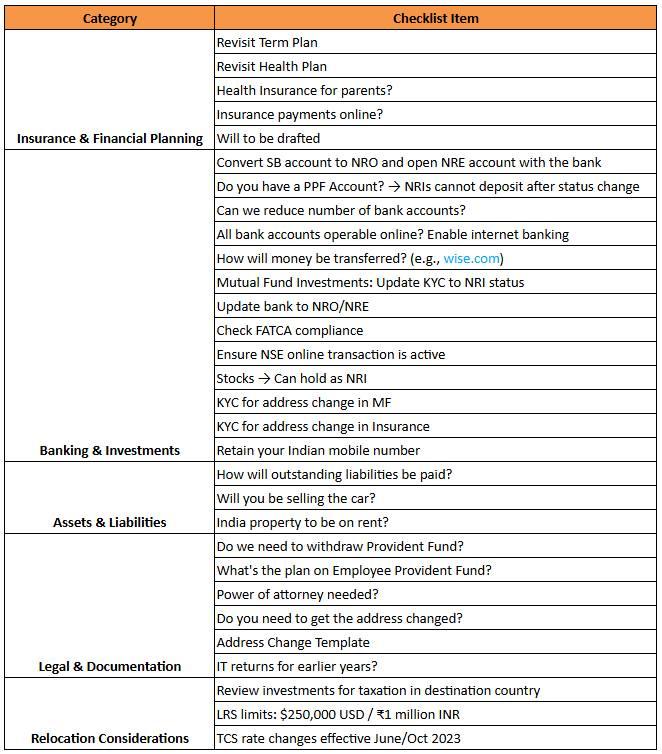
Checklist for Resident Indians (RIs) Moving Abroad and Becoming Non-Resident Indians (NRIs)
1. Banking & Financial Accounts
- Convert your resident savings accounts to Non-Resident External (NRE) or Non-Resident Ordinary (NRO) accounts.
- Consider opening a Foreign Currency Non-Resident (FCNR) deposit for foreign currency savings.
- Update KYC details with your bank, informing them of your NRI status.
- Close unnecessary resident savings accounts (NRIs cannot hold these).
2. Investments & Mutual Funds
- Update KYC status to NRI for all mutual fund holdings.
- Check with fund houses to see if they allow investments from your new country of residence. (Many AMCs restrict U.S. —and Canada-based NRIs.)
- Convert resident Demat & trading accounts to NRI Demat and Portfolio Investment Scheme (PIS) accounts if continuing to invest in Indian equities.
- Review tax implications on capital gains in both India and your new country of residence.
- Update bank mandate for dividend payouts to an NRO account.
3. Taxation & Compliance
- Check if you qualify as an NRI under the FEMA (staying abroad for more than 182 days) and Income Tax Act (considering previous financial years).
- File ITR as NRI from the next assessment year.
- Understand the Double Taxation Avoidance Agreement (DTAA) between India and your new country to avoid double taxation.
- If maintaining property in India, note TDS rules on rental income (30% TDS applicable).
- Ensure the correct Tax Residency Certificate (TRC) is obtained to claim DTAA benefits.
4. Property & Real Estate
- NRIs can continue to hold residential and commercial properties in India.
- If selling property, TDS deduction applies (20% on long-term capital gains for NRIs).
- Update property documents with your NRI status for smooth future transactions.
5. Insurance & Loans
- Convert life and health insurance policies to NRI status (check premium payment options).
- Review existing loans—NRI status can impact eligibility and terms of home loans, personal loans, etc.
- Check RBI regulations for repayment of loans as an NRI.
6. PAN & Aadhaar Updates
- Ensure your PAN is linked with Aadhaar (compulsory for tax filing).
- Update your address and contact details linked to PAN and Aadhaar.
- NRIs are not required to hold Aadhaar unless filing tax returns in India.
7. Remittances & Repatriation
- Use NRE accounts for easy repatriation of income earned abroad.
- Keep track of foreign remittance limits and reporting requirements under FEMA.
- Understand repatriation rules for sale proceeds of property, investments, and rental income.
- Under the Liberalized Remittance Scheme (LRS), resident Indians can remit up to USD 250,000 per financial year for permissible capital and current account transactions.
8. Estate & Will Planning
- Update nominee details for bank accounts, mutual funds, insurance, and Demat accounts.
- Consider making a Will to avoid complications in India regarding inheritance laws.
- If holding assets in India and abroad, consult a financial planner for estate planning.
9. Compliance for Returning NRIs (RNOR & Tax Status)
- If planning to return, understand Returning NRI (RNOR) status for tax exemptions.
- Plan for reinvestment of foreign income/assets upon return to India.
- Convert NRE/NRO accounts back to resident accounts when returning.
"If you're an NRI planning to return to India, timing your return smartly can help you qualify as RNOR and save taxes. Let's understand the key benefits of the RNOR status."
1. Extended RNOR Status with Smart Timing
RNOR status depends on when you return to India.
Example:
Return in July 2025 → RNOR for 2 years (FY 25–26 & 26–27).
Return in March 2026 → You are still NRI for FY 25–26, so you can claim RNOR for 3 years (FY 25–26, 26–27, 27–28).
2. Tax Advantage on Global Income
ROR (Resident & Ordinarily Resident): Taxed on worldwide income.
RNOR: Only Indian income is taxable.
This allows you to receive foreign income tax-free in India during RNOR years.
3. Lower Tax on Indian Investments
RNOR enjoys regular resident tax slabs, unlike NRIs who are often taxed at the highest rate on FD interest.
4. Wider Investment Options
RNORs can invest in:
· PPF (Public Provident Fund)
· Senior Citizen Savings Scheme
· Agricultural land (which NRIs cannot purchase)
5. RFC Account Benefits
RNORs can open and use RFC (Resident Foreign Currency) accounts.
Interest on RFC accounts is tax-free as long as you remain an RNOR.
NRI Sale of Property & Other Asset class Related FAQs
1) How do NRIs repatriate funds through Sale of Property?
Sale of Property:
- Residential Properties: NRIs can repatriate the sale proceeds of up to two residential properties.
- Commercial Properties: There are no specific limits, but repatriation is subject to overall repatriation limits and tax compliance.
- Conditions: Proceeds must be credited to an NRO account, and repatriation is subject to the USD 1 million limit per financial year. Taxes must be paid, and documentation (such as proof of purchase, sale, and tax payment) must be provided.
2) What are the issues with Real Estate for NRIs?
Buying multiple properties in India is not efficient from the taxation perspective. Only one property can be shown as self-occupied. The other has to be rented out, and rental income is taxable; if not rented out, it is considered deemed let-out, and the deemed rent is taxable. Investors not showing rental income from multiple properties becomes an issue with Indian tax compliance.
Tracking of properties held by Indian residents and NRIs is difficult and, hence, real estate investors have always been flying under the radar of tax authorities. NRIs/PIOs/OCIs are big investors in Indian real estate; they have to worry whether FATCA will apply to real estate holdings in future. The issue, again, is that income from real estate may not have been reported in the US tax returns and, hence, NRIs may not want to reveal that they did not report the Indian rental income in US tax returns. With fear of FATCA, NRIs are trying to come clean before they get caught.
Property Buying Fraught with Unclear Title Issues
Real estate has been a popular investment option for NRIs/PIOs/OCIs. They are allowed to invest in residential and commercial properties with NRO/NRE accounts to make payments but cannot invest in agricultural land, farmhouses, or plantations in India. NRIs can own such properties only if they have been inherited, but they can sell such properties only to a resident Indian.
With the real estate market in India going through a downturn, NRIs should be wary of buying property as an investment. Moreover, buying property in India can have issues of legalities and clear titles. Do check that the property has all the required approvals from civic authorities for construction. It is not easy for a novice to buy property without hassles. Having the ‘right’ intermediary can help to check the documentation and do proper title search and transfer; but agents are unregistered and, hence, service levels can vary. NRIs can avail home loan from Indian banks or financial institutions after satisfying the eligibility criteria. The loan amount and repayment transactions are in Indian rupees.
Property Selling Can Trouble You with Capital Gains Abroad
Property is an illiquid asset. It is not easy to sell in a down market without taking a beating. Selling property comes with some restrictions by FEMA (Foreign Exchange Management Act), especially for repatriation transactions. The property transaction can generate a high amount of capital gains which can create taxation issues especially for NRIs, depending on the country of residence.
Taxation on capital gains in India can be avoided by buying another property or investing in capital gains savings bonds from the Rural Electrification Corporation (REC) and the National Highways Authority of India (NHAI). But your country of residence may not accept such an arrangement. For example, a foreign resident may save taxes on property sold in India by re-investing in property or buying such bonds. But it may not be allowed under tax laws of the foreign country where the NRI resides. The capital gains made zero in India may mean that full capital gains will have to be paid in the foreign country.
Unlike India, the foreign country may not even allow the calculation of inflation-indexed purchase price to lower your capital gains. If such adjustment is not allowed, your capital gains abroad can be much higher than the capital gains calculated for Indian tax laws. It is crucial to consider if the income-tax liability in the country of residence on the capital gains will nullify the tax savings you made to satisfy the Indian tax laws. You will wonder whether claiming exemption under Sections 54/54F/54EC was really the correct decision.
If you end up saving taxes in India, but paying in your country of residence, your tax saving may not materialise. The NRI may be better off claiming only partial or no tax savings at all in India. Buying property in India may seem unattractive when you consider the tax angle in your country of residence. So, don’t jump into buying property without knowing the tax issues when you exit.
3) Property on Rent – Is Tax Deducted at Source?
Renting your property with a ‘leave and licence’ (L&L) agreement can be better than giving your property without any paperwork. Registering and paying stamp duty on the L&L agreement can ensure your right as the owner. The police can help you as the property owner if you have a registered L&L agreement. If you don’t have an agreement, it may be tougher to get justice.
Power of Attorney (PoA): When you are an NRI, you have the additional burden of giving a PoA to one of your family members to execute the L&L agreement, in your absence. You may not be able to personally meet the licensee to know him/her before renting It is a disadvantage. There is always fear of the licensee not vacating the place, despite signing an L&L agreement and registering it.
TDS on Rent: Under L&L agreement, a licensee is required to deduct tax at source at 30.9% under Section 195 before making the balance rental payment to the NRI owner. The licensee needs to pay the rent directly into the NRO account. The TDS by L&L licensee can be a turn-off for both parties, even though the owner is liable to be taxed on the rental income and can even get a refund if the income from Indian sources is below the minimum slab rate.
4) How do NRIs repatriate funds through Sale of Shares and Securities?
Sale of Shares and Securities:
- Repatriability: NRIs can repatriate sale proceeds after paying applicable taxes.
- Conditions: Investments must be made on a repatriable basis (through NRE/FCNR accounts). The transaction should be routed through a registered stockbroker.
Portfolio Investment Scheme (PIS)
1) What is PIS (Portfolio Investment Scheme)?
The Reserve Bank of India (RBI) allows NRIs and overseas citizens of India (OCI)/persons of Indian origin (PIOs) to invest in the Indian equity markets under PIS (portfolio investment scheme). PIS is a foreign investment route to simplify the process of registration and investment for all foreign investors. NRIs/OCIs/PIOs can purchase or sell the shares/NCDs (non-convertible debentures) of Indian companies on the stock exchange. This can be done by following these steps:
a. Bank Account: You need an NRE (non-resident external) or NRO (non-resident ordinary) account and obtain approval for stock trading under PIS.
b. Demat and Trading Account: You need a trading account (linked to the PIS account) with a broker and demat account by any service-provider.
Many banks have started offering all the above-mentioned services at a single point, which has made this process smooth. NRIs need to keep in mind the following:
- Only one PIS account can be opened for buying and selling of shares;
- Stock investment cannot exceed 10% of the paid-up capital of the company;
- Intraday trading not allowed. NRIs have to take delivery of shares purchased/sold;
- Short-selling not allowed;
- Can invest in only selected stocks as listed by RBI periodically;
- Investment can be done on repatriation as well as non-repatriation basis.
The following transactions do not need PIS account.
a. Sale of shares, which were not bought under PIS. For example, gifts, subscription to IPOs or shares bought as resident Indian, or received as bonus;
b. Fresh subscription for IPOs as an NRI;
c. Investment in MFs.
An NRI is eligible to subscribe toMutual Funds and Bonds in india. However, the issuer should specifically enable the ‘NRI Window’ in an offer. The bonds can be tax-free bonds or taxable. They can be subscribed on both repatriable and non-repatriable bases. NRIs can apply for these bonds through their NRE/NRO accounts. To apply on a repatriable basis, you need to fund it from an NRE account. For non-repatriable basis, apply from an NRO account.
Exchange Traded Funds (ETFs): Investment can also be done in ETFs available in India with your PIS account through your NRE/NRO bank account. However, investors from the US may want to avoid buying ETFs as they are considered PFIC (passive foreign investment companies), as discussed later in this article. Even investment in shares of companies considered as PFIC should be avoided by a US resident/person.
Direct vs Regular Mutual Funds
1) What is the impact on returns with respect to Direct & Regular Mutual Funds?
When investing in mutual funds, NRIs (Non-Resident Indians) and resident investors in India have the option to choose between direct plans and regular plans. The choice between these two types of plans can significantly impact the returns on investment.
Direct Plans
Definition: Direct plans are mutual fund schemes where investors can invest directly with the fund house without involving any intermediaries or brokers.
Key Features:
- No Distributor Commission.
- Lower Expense Ratio.
- Higher NAV (Net Asset Value).
Advantages:
- Higher Returns.
- Transparency.
Disadvantages:
- Do it yourself (DIY) Approach.
- No Advisory Services.
Regular Plans
Definition: Regular plans are mutual fund schemes where investors invest through intermediaries such as brokers, agents, or distributors.
Key Features:
- There will be Distributor Commission involved.
- Higher Expense Ratio.
- Lower NAV.
Advantages:
- Professional Advice.
- Convenience on documentation, paperwork, redemption etc.
Disadvantages:
- Lower Returns.
- Higher Costs.
Impact on Returns
The primary difference between direct and regular plans lies in the expense ratio, which directly impacts the returns. Here’s a simplified example to illustrate the impact:
- Assume: An investment of ₹1,00,000 in both direct and regular plans of the same mutual fund.
- Direct Plan Expense Ratio: 1.0%
- Regular Plan Expense Ratio: 1.5%
Returns After One Year(assuming a 10% gross return on investment):
1) Direct Plan:
- Gross Return: ₹1,00,000 x 10% = ₹10,000
- Expense Ratio Cost: ₹1,00,000 x 1.0% = ₹1,000
- Net Return: ₹10,000 - ₹1,000 = ₹9,000
- Ending Balance: ₹1,00,000 + ₹9,000 = ₹1,09,000
2) Regular Plan:
- Gross Return: ₹1,00,000 x 10% = ₹10,000
- Expense Ratio Cost: ₹1,00,000 x 1.75% = ₹1,750
- Net Return: ₹10,000 - ₹1,750 = ₹8,250
- Ending Balance: ₹1,00,000 + ₹8,250 = ₹1,08,250
Difference in Returns:
- Direct Plan Ending Balance: ₹1,09,000
- Regular Plan Ending Balance: ₹1,08,250
- Difference: ₹1,09,000 - ₹1,08,250 = ₹750
Over time, this difference compounds, leading to significantly higher returns in direct plans compared to regular plans.
Strategy used for Mutual Fund Investment & Return Expectations
Checklist for NRIs Returning to India
1. Banking & Financial Accounts
- Convert NRE/NRO accounts back to resident savings accounts.
- Close any unnecessary NRE/NRO accounts as per RBI guidelines.
- Consider opening anResident Foreign Currency (RFC) account to park foreign earnings in India.
- Update KYC details in all Indian bank accounts with a new residential status.
2. Investments & Mutual Funds
- Convert NRI Demat & trading accounts back to resident status.
- Update KYC details with mutual fund houses to reflect resident status.
- Reassess investments and modify portfolio allocation based on Indian tax laws.
- If applicable, check LTCG (Long Term Capital Gains) tax implications on overseas investments.
- NRIs returning to India can bring back proceeds from US investments subject to FEMA regulations. The annual exemption limit for repatriation varies based on tax treaties and reporting requirements.
- Under RBI's LRS (Liberalized Remittance Scheme), returning NRIs can remit up to USD 250,000 per financial year.
3. Taxation & Compliance
- Understand the Returning NRI (RNOR) status and tax benefits for the transition period.
- RNOR (Resident but Not Ordinarily Resident) status applies for up to two years post-return, offering tax exemptions on foreign income.
- Income earned outside India is not taxable in India during the RNOR period, except if received in India.
- RNORs are exempt from global income taxation but must comply with Indian tax laws after the RNOR period ends.
- Update PAN card details with the new residential status.
- File ITR as a resident Indian for the next assessment year.
- Declare all foreign assets and income in tax filings to comply with Indian tax laws.
- Check applicability of Double Taxation Avoidance Agreement (DTAA) for foreign income.
- Obtain a Tax Residency Certificate (TRC) if required to claim DTAA benefits.
4. Property & Real Estate
- Update home address in property documents, utility bills, and Aadhaar.
- Check capital gains tax liability if selling property abroad before moving back.
- If renting out property abroad, review taxation under Foreign Income Tax Act.
- Consider repatriating proceeds from property sales under FEMA guidelines.
5. Insurance & Loans
- Update life and health insurance policies with a new residential status.
- Convert existing international health insurance to an Indian equivalent if required.
- Reassess home loans, personal loans, and credit card payments in both countries.
- Check RBI regulations for foreign loans repayment and mortgage status.
6. PAN & Aadhaar Updates
- Ensure your PAN is linked with Aadhaar for tax compliance.
- Update address and contact details linked to PAN and Aadhaar.
- Apply for an Aadhaar card if not previously obtained, as it may be required for banking and taxation.
7. Foreign Assets & Repatriation
- Plan for repatriation of foreign earnings through legal channels.
- Understand FEMA limits for remittance and reporting requirements.
- If holding significant overseas assets, consult a financial planner for tax-efficient transfer.
- NRIs can repatriate investment proceeds from US stocks, mutual funds, and real estate, subject to IRS & FEMA rules. Ensure compliance with capital gains tax rules in both countries.
- Close unnecessary foreign bank accounts if no longer needed.
8. Estate & Will Planning
- Update nominee details for bank accounts, investments, and insurance policies.
- Modify or create a new Will reflecting your change in residency and asset locations.
- Ensure compliance with Indian succession laws for foreign assets.
9. Employment & Business Transition
- Inform employer and update tax withholding details if returning permanently.
- If self-employed or holding an overseas business, assess tax and legal implications.
- Transfer professional credentials/licenses to India if required for work.
10. Social Security & Retirement Planning
- Check eligibility for pension withdrawals or transfers from overseas funds.
- Understand Social Security benefits (like U.S. Social Security) and whether you can claim them in India.
- Plan for retirement savings in India by investing in suitable schemes like EPF, PPF, or NPS.
11. Family & Education Considerations
- If moving with children, review school/university admission procedures in India.
- Ensure all family members have updated documents (passports, Aadhaar, PAN, etc.).
- Plan for any dependent family members’ healthcare and insurance needs.
1) Which Mode of investing is suggested for NRIs either SIPs or STPs?
Systematic Transfer Plans (STPs) are investment strategies that allow investors to transfer a fixed amount of money at regular intervals from one mutual fund to another, typically from a debt fund to an equity fund. For NRIs (Non-Resident Indians), STPs can offer both strategic benefits and tax implications that need careful consideration.
Benefits of STPs for NRIs
- Rupee Cost Averaging: STPs help in averaging out the purchase cost by investing regularly in equity funds, reducing the impact of market volatility.
- Consistent Investment: Helps in maintaining discipline by ensuring regular investment without the need to time the market.
Considerations for NRIs Using STPs
1) Tax Deducted at Source (TDS):
- For NRIs, mutual fund houses in India deduct TDS on capital gains.
- Debt Funds: TDS at 30% on STCG and 20% on LTCG.
- Equity Funds: TDS at 15% on STCG and 10% on LTCG (on gains exceeding ₹1 lakh).
In case the client is not ready for the TDS deduction, which is on the capital gain part, then the same benefits can be availed while keeping the lumpsum in a savings bank account and doing a weekly SIP instead of STPs.The only disadvantage of doing this is that the investor won’t get higher returns, which most of the liquid or Arbitrage funds offer.The average return that a liquid or arbitrage funds offer is around 5% ~ 8%, p.a. whereas in a savings account, we can expect around 3% ~ 4% p.a.
2) What are the return expectations for various risk profiles?
Based on individual risk profile and risk taking ability, we can broadly classify the risk profiles as follows:
- Very Conservative Risk Profile (7% - 9%)
- Conservative Risk Profile (8% - 10%)
- Moderate/Balanced Risk Profile (9% - 12%)
- Aggressive (10% - 13%)
- Very Aggressive (14% - 18%)